Daily Market Digest · Thursday, October 8, 2026
The squeeze tightened from both sides.
Built from tonight's finance podcast transcripts — what the shows actually said, paraphrased, never invented. Sources that weren't available are marked inline.
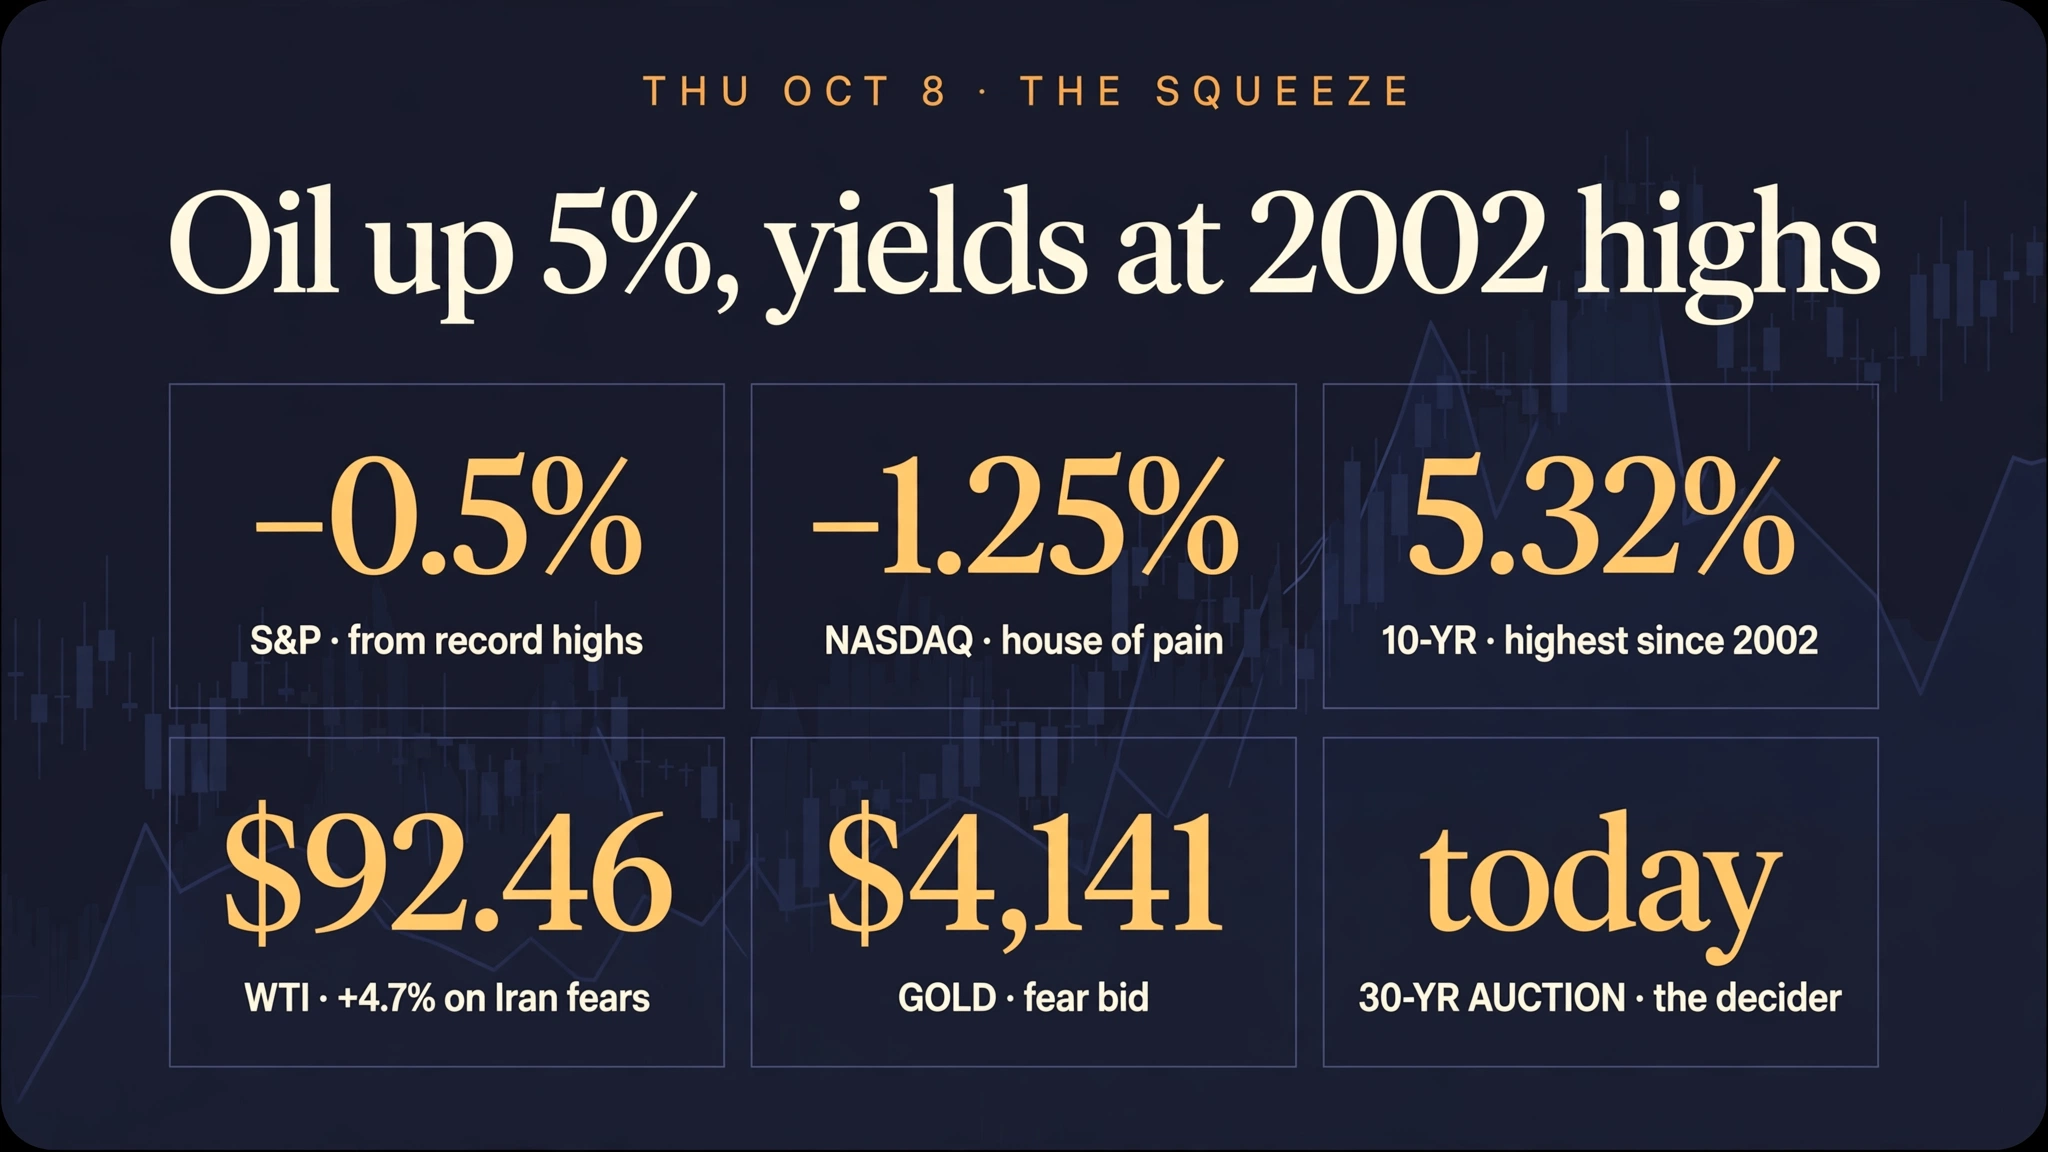
The one thing that matters: the squeeze tightened from two directions at once — crude surged ~5% on reports of potential US strikes on Iran and stepped-up Houthi attacks on Saudi infrastructure, while Treasury yields marched to their highest since 2002 (10Y ~5.3%) with Fed Governor Waller publicly backing more hikes. And yet the bond market barely blinked at a strong $39B 10-year auction — while the AI debt binge (Broadcom lining up $50B+ for OpenAI chip purchases, Oracle, SpaceX) collided with today's 30-year auction. The day's consensus: orderly so far, but nobody can find the circuit breaker.
Schwab Market Update
"Stocks Slide Early as Oil, Yields March Higher" — morning edition, Oct 8, 9:13am ET (via search-index cache; schwab.com bot wall as usual)
- Pre-open snapshot (Thursday market open): S&P 500 7,801.74 (−0.22%), Dow 51,179.87 (−0.66%), Nasdaq 27,538.69 (−0.22%), 10-year 5.32% (+0.05), dollar index 102.37, VIX 15.70 (+4.11%), gold $4,141.30, WTI crude $92.46 (+4.73%), Bitcoin $82,167 (−1.33%). Rising oil and yields pushed stocks lower again early Thursday.
- Signs of escalation in the Middle East sent oil about 5% higher; yields got a boost from Fed Governor Christopher Waller's statement that multiple rate increases might be needed to tame inflation "within an acceptable period of time."
- Stocks fell Wednesday, seven of 11 S&P sectors losing ground, a day after the index closed at a record high.
- 10-year and 30-year yields hit their highest level since 2002 Wednesday, then retreated after an auction of 10-year notes found strong demand.
- The day's watch item: today's 30-year bond auction — the next read on whether demand can absorb the supply at these yields.
The day's market callDefensive tape — oil and yields are the whole story; watch today's 30-year auction and next week's CPI for the next yield move.
Tickers: SPX, DJI, NDX, WTI, GLD, BTC
Bloomberg: The Big Take
"The UK's $160 billion billionaire exodus" — host Sarah Holder with Bloomberg's Benjamin Stupples; description-level (no full transcript available)
- Ultra-wealthy individuals are fleeing the UK after sweeping Labour Party tax reforms cracked down on overseas wealth — the episode frames it as the biggest population shift of the ultra-wealthy the reporter has covered in 10 years.
- New data from the Bloomberg Billionaires Index sizes the exodus at ~$160 billion of wealth at stake.
- The frame: a wealth-tax-policy story about Britain's economic attractiveness to the rich — not a markets/trading story, but the capital-flight angle feeds the same global yield-and-policy conversation running through today's other shows.
The day's market callNo market call — a tax-policy story, not a trading story.
Tickers: none
Bloomberg Surveillance (TV)
"Bloomberg Surveillance 10/8/2026" — full-day TV program, Oct 8; full transcript via auto-captions
- The day's thesis: "there clearly is a problem with the sovereign bond market — and yet the corporate bond market remains completely open," as AI borrowers (Oracle, Broadcom, SpaceX) keep lining up deals even at 2002-era yields. Why isn't the sovereign meltdown infecting the broader market yet? That's the confusion everyone's trying to understand.
- Yields: 10Y ~5.32–5.35%, 30Y ~5.7%; one guest's call: "we can easily see yields getting to 5.5% here." Estimates suggest the rise has been underestimated because of just how robust AI-driven demand is proving.
- France is near the danger zone: 10Y ~4.9%, spread over Germany ~140–150bp, 38% of French corporates now trading inside the sovereign. The ECB declined to step in — a governance crisis, "symptomatic of the Western world."
- Waller endorsed more hikes for a "timelier" return to 2%, with flexibility on pacing — ~50bp could come early next year. The October hike door is closed; the next CPI (Oct 14) and December are the decision points.
- The AI credit binge continues unabated: Broadcom arranging $50B+ (Apollo, Blackstone) for OpenAI chip purchases; Oracle and SpaceX also tapping markets. Spreads are starting to widen on some deals — CreditSights sees cracks but no near-term Oracle downgrade.
- Morgan Stanley's Moore: memory shortage constrains builds — "AI will use all supply" — kept a $300 Nvidia price target; the AI trade is a duration bet: 2027 growth of 70–90% still on the table.
- BlackRock's Rieder is loving front-end real rates and buying IG credit, avoiding duration. Expects a December hike; suggested the Fed may eventually need to cap long-end yields directly (yield-curve-control-like), since hiking the funds rate barely dents GPU buying.
- Columbia Threadneedle: "dangerous moment" — 3–4 more hikes may be needed; hyperscaler IG bonds "getting punished"; AI borrowers are not as rate-insensitive as believed. Pain is already showing in housing (7.5% mortgages), high-yield, and loan markets.
The day's market callRisk-off grind — equities under pressure from yields and oil until the 30Y auction clears and Oct 14 CPI prints; credit cracks emerging but orderly, no meltdown yet.
Tickers: AVGO, ORCL, NVDA, MSFT, META, GOOGL, NFLX, PLTR, RCL, PEP, TSM, MU, AMD, INTC, AMAT, LRCX, KLIC, STM, WOLF, APLD, LEVI, GS, MS, JPM, BX, APO
Bloomberg Surveillance (radio)
"US Suspends Visa Program for Tech Firms, Mideast Fighting Spurs Inflation Fears" — Oct 8 radio podcast; full transcript via auto-captions
- White House "New Golden Age" science summit: Trump awarded science medals to Musk, Jensen Huang, and Lisa Su; companies committed ~$2.4B in computing power, plus $100M+ for STEM education.
- The US is suspending a visa program for tech firms (incl. Microsoft) that lets H-1B workers move toward green cards — targeted as abuse-prone and disadvantaging US workers; awkward timing with Microsoft's Nadella receiving a medal at the same event.
- Dr. Ellen Wald (energy): Brent back above $105 as fresh Iranian tanker attacks collide with a Gulf hurricane that shut ~25% of US offshore crude. With stocks and SPRs exhausted, oil is "locked into a higher range"; Aramco is formalizing a Hormuz-bypass shuttle system for 2026 contracts — a sign it views the conflict as long-term.
- Claudia Sahm: the "curious balance" — jobless claims under 200K (197K today) but 3-month payrolls only ~50K; quits rate near lows, workers lack leverage, real wages lagging as inflation picks back up. AI is at most a marginal hiring drag — the bigger factor is business uncertainty.
- An FT report that OpenAI's revenue may be ~$20B below expectations rattled AI-spend justification — S&P −0.6%, Nasdaq −1.3%, semiconductor index −3%; 10Y 5.23%, 30Y 5.60%, gold $4,123/oz.
- Stock movers: Chipotle (CMG) +6–7% on an FT report that Starbucks explored a takeover — a Brian Niccol reunion play; Starbucks (SBUX) −2.5% on deal-skepticism. Levi's (LEVI) −2.5% on the slowest direct-to-consumer growth since 2022. Latham (SWIM) −5% on a William Blair downgrade — high yields freezing pool spending.
The day's market callOil → inflation fears → rate-hike pricing is the tape; equities near session lows with AI-spend anxiety joining the mix.
Tickers: MSFT, NVDA, AMD, TSLA, CMG, SBUX, LEVI, SWIM, GS, META, GOOGL
Mad Money
"Mad Money 10/08/26 | Audio Only" — Jim Cramer; full transcript via YouTube auto-captions
- Market recap: Dow +52, S&P −0.47%, Nasdaq −1.25% ("house of pain"). The FT story that OpenAI revenue could be ~$20B short crushed the AI data complex (Nvidia, Broadcom, Google) — Cramer called it a charnel house, with no confirmation from OpenAI that the story is wrong.
- The lesson was diversification: with AI down, Home Depot jumped ~3% after the 30Y auction ended — buy out-of-favor HD at under 19x next-year earnings with a 3.15% yield; he sees $400 when rates eventually come down.
- McDonald's (~$231, 17.2x next-year earnings, cheapest since 2014): likes the stock but worries about franchise buy-in for the turnaround plan; suggested buying in thirds — low $230s, sub-$230, and at $200 if it breaks.
- Agnico Eagle CEO Amar Aljundi on gold (~$4,200/oz, up from $250 in 2000): central banks are the biggest buyers because they fear losing access to dollar reserves; the miner has tripled production per share over 20 years. Governments can control Bitcoin but not gold — currency sovereignty is the case for gold.
- PepsiCo rallied +3.7% despite cutting full-year core EPS growth from 5–7% to 2.5–3.5% — the cut was fully priced in after an 8-month, 28% slide, and the quarter beat ($2.34 EPS, organic revenue +3.1%). Investing in price cuts and marketing is working on volumes; margins are being squeezed by fuel and packaging. At 15x new guidance with a 4.6% yield: "you could do a lot worse."
- Everpure (renamed from Pure Storage), up 125% YTD: hyperscale storage business "exploding" with visibility through FY28/29; uses raw flash (not SSDs) for a power/performance edge; touted an industry-leading 84 net promoter score.
- Lightning round: liked Kulicke & Soffa (KLIC) on weakness but prefers Lam Research #1, Applied Materials #2; STMicro is fine but buy Intel at ~$107 for the 2028 story; passed on Celsius — execution problem, not a buy; Valuations segment: at ~6% bond yields, future earnings are worth less — money-losing growth stocks look expensive; SpaceX is a company he loves but a stock that's overvalued — buy only on substantial weakness.
The day's market callStay diversified — own cash and non-AI names to ride out days like this; the AI trade should bounce back once the OpenAI revenue fog clears; cheap staples (MCD, PEP, HD) are buys on weakness.
Tickers: MCD, HD, NVDA, AVGO, GOOGL, MSFT, AXP, AEM, PEP, PSTG, KLIC, LRCX, AMAT, STM, INTC, CELH, STZ
Fidelity Market Sense
No new episode
Latest episode ("How has the market performed during midterm elections?", Oct 6) was covered in the Oct 7 edition. Fidelity drops Tuesdays; nothing new since.
Fast Money
Skipped
No free caption source — standing rule; never summarized from headlines.