Daily Market Digest · Friday, September 25, 2026
The selloff faded. AI's wrecking ball kept swinging.
Built from tonight's finance podcast transcripts — what the shows actually said, paraphrased, never invented. Sources that weren't available are marked inline.
The one thing that matters: Friday's tape calmed down — the bond selloff faded as the 10-year backed off its overnight highs to 5.17%, and oil fell 2.3% on hopes the U.S. and Iran can phase open the Strait of Hormuz. But the week's real story stayed intact: AI is now the market's wrecking ball. Meta's Muse agent is grinding down "consumer inertia" stocks (Planet Fitness, the New York Times, Schwab, LPL, TripAdvisor, Booking), 60–70% of hyperscaler capex is flowing into data-center gear, and one desk argues that same AI build-out is what's pushing real yields higher. Calm surface, tectonic undercurrent.
Schwab Market Update
Friday, Sept 25 · Morning edition (9:13 a.m. ET) — "Stocks Up on Oil, Yields, Tracking for Weekly Rise." Schwab's written daily article; morning snapshot below. Full body not retrievable tonight (site bot wall), so headline and snapshot only.
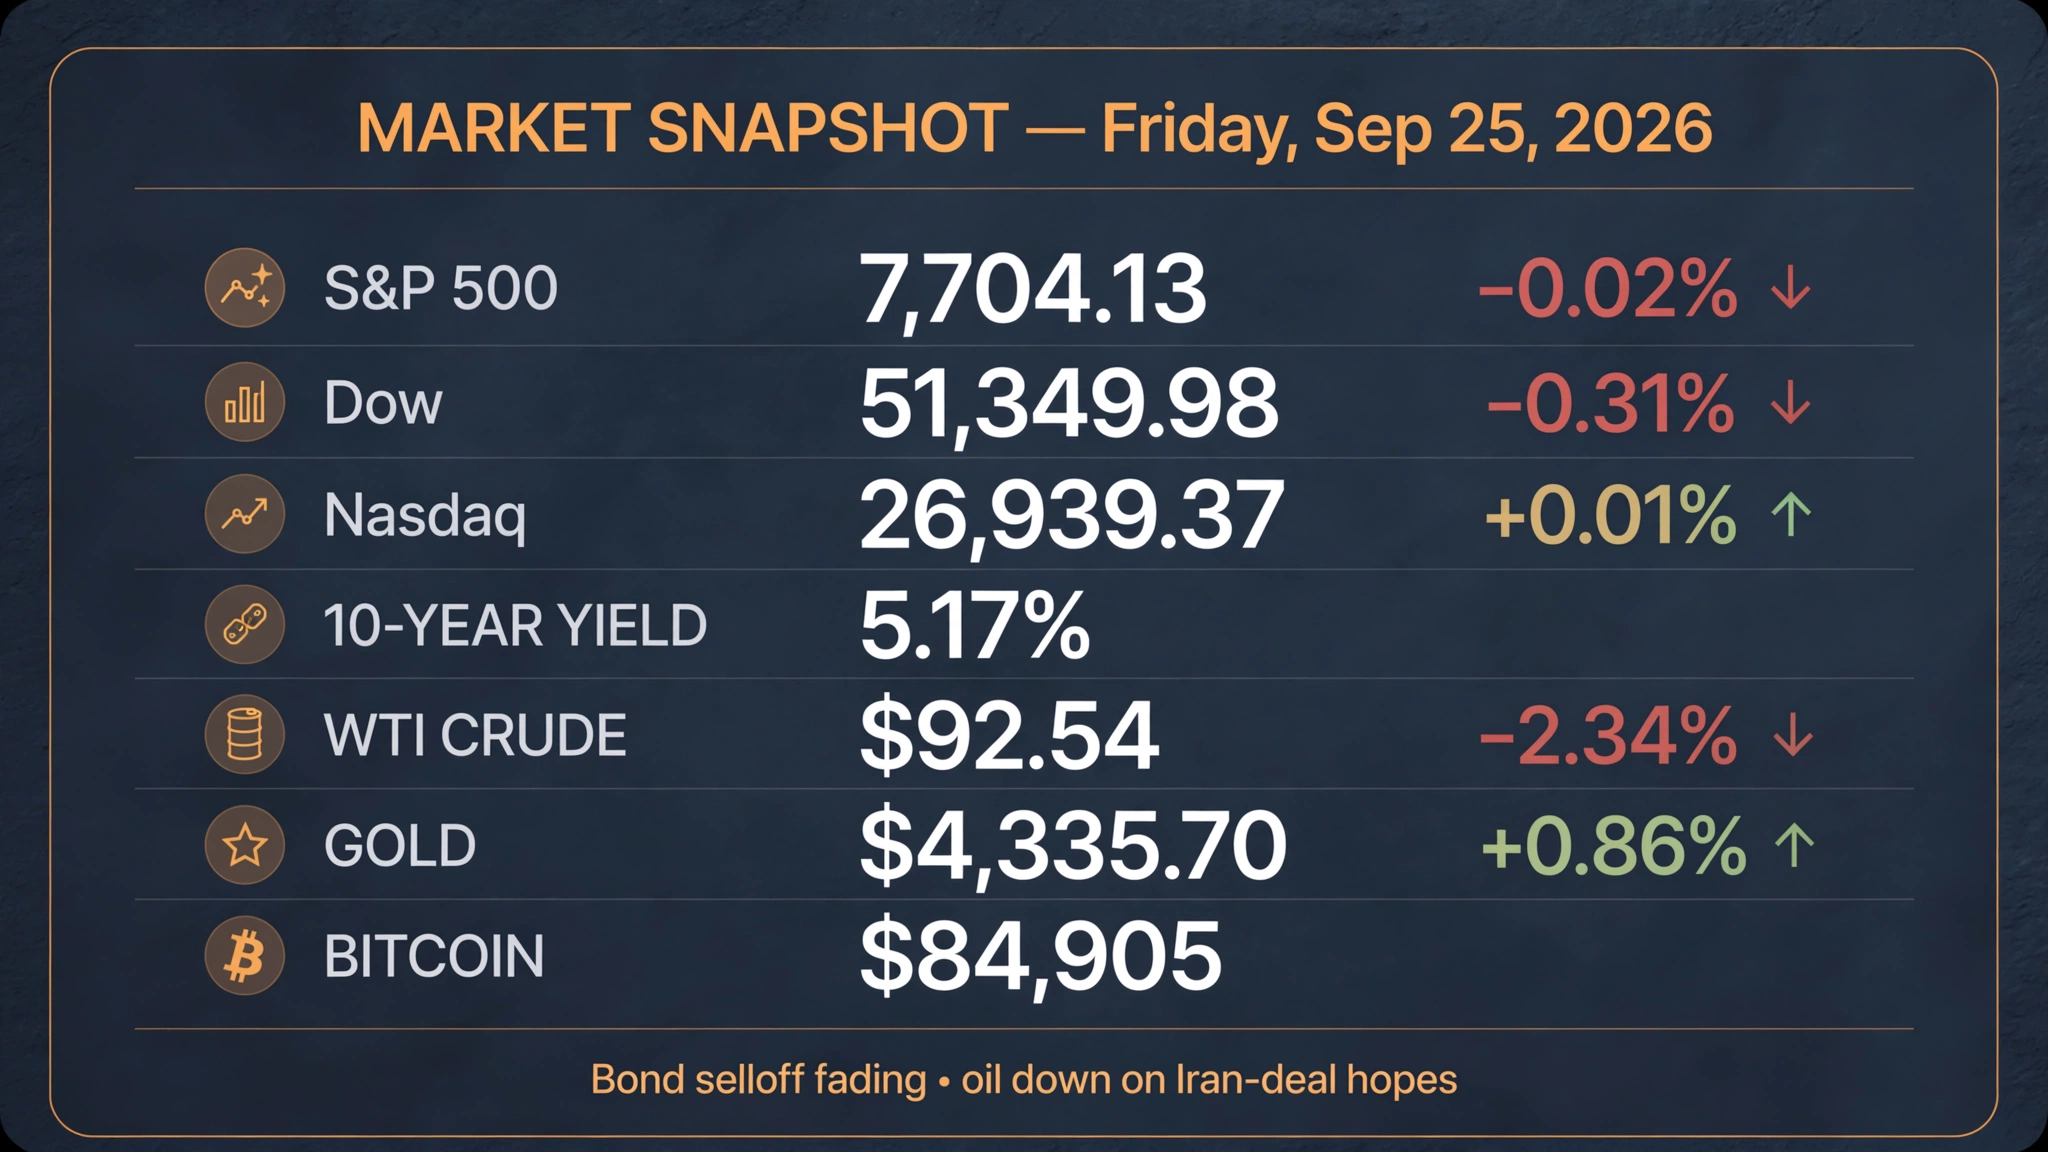
- Morning tape: S&P 500 7,704.13 (−0.02%), Dow 51,349.98 (−0.31%), Nasdaq 26,939.37 (+0.01%). 10-year Treasury yield 5.17% (+0.02, near 19-year highs); Dollar Index 100.98 (−0.30%); VIX 15.22 (−2.87%); gold $4,335.70 (+$37, +0.86%); WTI crude $92.54 (−$2.07, −2.34%); Bitcoin $84,905.
- The story: stocks edged up early, keeping the S&P on pace for a positive week despite the dramatic rally in yields — which gave back their steepest overnight gains, aiding stocks.
- Oil on Iran-deal hopes: WTI down over 2% after Reuters reported the U.S. and Iran had discussed a phased reopening of the Strait of Hormuz and an end to the U.S. blockade of Iran; NBC reported Iran's president is willing to make a deal before the U.S. midterms.
- Trump–Xi: meetings between U.S. and Chinese leaders "failed to forge any trade breakthroughs," keeping geopolitics front and center.
- Next week: a fresh monthly jobs report puts the economy center stage, plus earnings from Micron (MU) and Nike (NKE).
The day's market callYields near 19-year highs yet stocks resilient — the climb has been orderly and inflation is only slightly high. Geopolitics (Iran, China) is the swing factor into the weekend.
Tickers: SPX, DJIA, COMP, TNX, DXY, VIX, GC, WTI, BTC. MU, NKE report next week.
Bloomberg Surveillance
Friday, Sept 25 · Radio: "Bond Selloff Fades as Oil Cools; Trump-Xi Takeaways." Tom Keene & Paul Sweeney with Michael Gapen (Morgan Stanley, chief U.S. economist), Lindsay Newman (Chatham House), Darius Dale (42 Macro), Karan Sood (Vest). Full transcript via auto-captions. The TV broadcast's chapter list echoed the same themes (notes where sourced from chapters, not transcript).
- Dale's 2027 bull case: a productivity boom plus a jobless recovery should equal margin expansion, which should equal multiple expansion — and he expects liquidity to arrive and drive a multiple rerating. The volatility since early June, in his view, is a "coiled spring," and 42 Macro is "so bullish when we look out into 2027."
- The AI capex math: roughly 60–70% of hyperscaler spending goes to computers and peripherals — the gear inside data centers. Like past tech revolutions, there's a boom-bust arc: tremendous acceleration, then the question is why and how fast spending slows, and which winners and losers get revealed.
- No decoupling: Newman says nobody talks about decoupling anymore — the conversation is about how deeply intertwined the U.S. and China are: critical minerals one way, chips the other, and "super intelligence" (AI) as the other big front.
- On bonds: Dale's read is that a modest monetary debasement ran through June and that something material — Treasury buybacks with TGA funding, reserve-management purchases, or Fed yield curve control — would be needed for more; his fair-value model on the 10-year is the signal to watch.
- Investor certainty: Vest's Karan Sood on structured investing — when your bills come due your investments have to be there, and that certainty "has a certain utility for investors."
- From the TV chapter list: the Mag 7 trade is back (Roundhill's Drew Pettit), AI CapEx is pushing real yields higher (PIMCO's Lotfi Karoui), "today's diesel prices are tomorrow's core inflation" (Apollo's Torsten Slok), and rates aren't restrictive yet (BofA's Meghan Swiber).
The day's market callThe bond selloff fading + oil cooling is relief, not resolution. The desk's debate is now structural: AI capex is simultaneously the growth engine and the thing keeping real yields elevated.
Tickers: none individual. Mag 7, 10Y real yields, diesel/oil as inflation proxies.
Bloomberg The Big Take
Friday, Sept 25 · No confirmed 09-25 episode found — the Big Take drops every afternoon but tonight's episode couldn't be confirmed, so the show is skipped rather than summarized from headlines.
Big Take transcript not up yet.
Fidelity Market Sense
Weekly — drops Tuesdays. No new episode since Week 212 (2026-09-15).
CNBC Mad Money
Friday, Sept 25 · "Mad Money 09/25/26 | Audio Only." Full auto-captions. A Friday wisdom/teach-in episode — Cramer walked through accumulated investing rules plus Q&A from Investing Club members.
- Believe executives who pre-announce bad news: "they don't like slash numbers" — they cut because they don't see things improving by next quarter. Bad news usually takes at least a month to get fully baked into the stock, and it's okay to start buying after that.
- The baby-and-bathwater trade: when the worst company in an industry reports bad numbers, the whole group sells off even if everyone else is fine — that's an opportunity. His example: the April 2023 cybersecurity selloff led by Tenable (TENB) turned out to be "one of the greatest opportunities ever" to buy Palo Alto Networks (PANW). Caveat: markets can stay irrational longer than you can stay solvent.
- Ignore the recession narrative: the narrative "flip-flops back and forth between recession and strength" — Cramer says gaming that chatter is a big mistake and keeps people out of the market. Look for high-quality growth companies that do well in thick or thin.
- Deploy cash gently: with sizable cash on the sidelines, don't go all in — wait for weakness, buy a small position, see if it keeps going lower. "Don't just like, okay, this is the level I'm in."
- Emotional discipline: getting mad at yourself on down days isn't sustainable — you'll run out of patience and give up on the asset class.
The day's market callNo stock picks tonight — a process episode. The takeaway: let bad news bake in (~a month), buy industry baby-with-bathwater selloffs, and ignore the recession-vs-strength noise.
Tickers: PANW (Palo Alto Networks), TENB (Tenable). Charitable Trust / Investing Club referenced; no new picks.
CNBC Fast Money
Skipped — no free caption source (standing rule).