Daily Market Digest · Thursday, September 24, 2026
The summit delivered a truce. The bond market delivered the tape.
Built from tonight's finance podcast transcripts — what the shows actually said, paraphrased, never invented. Sources that weren't available are marked inline.
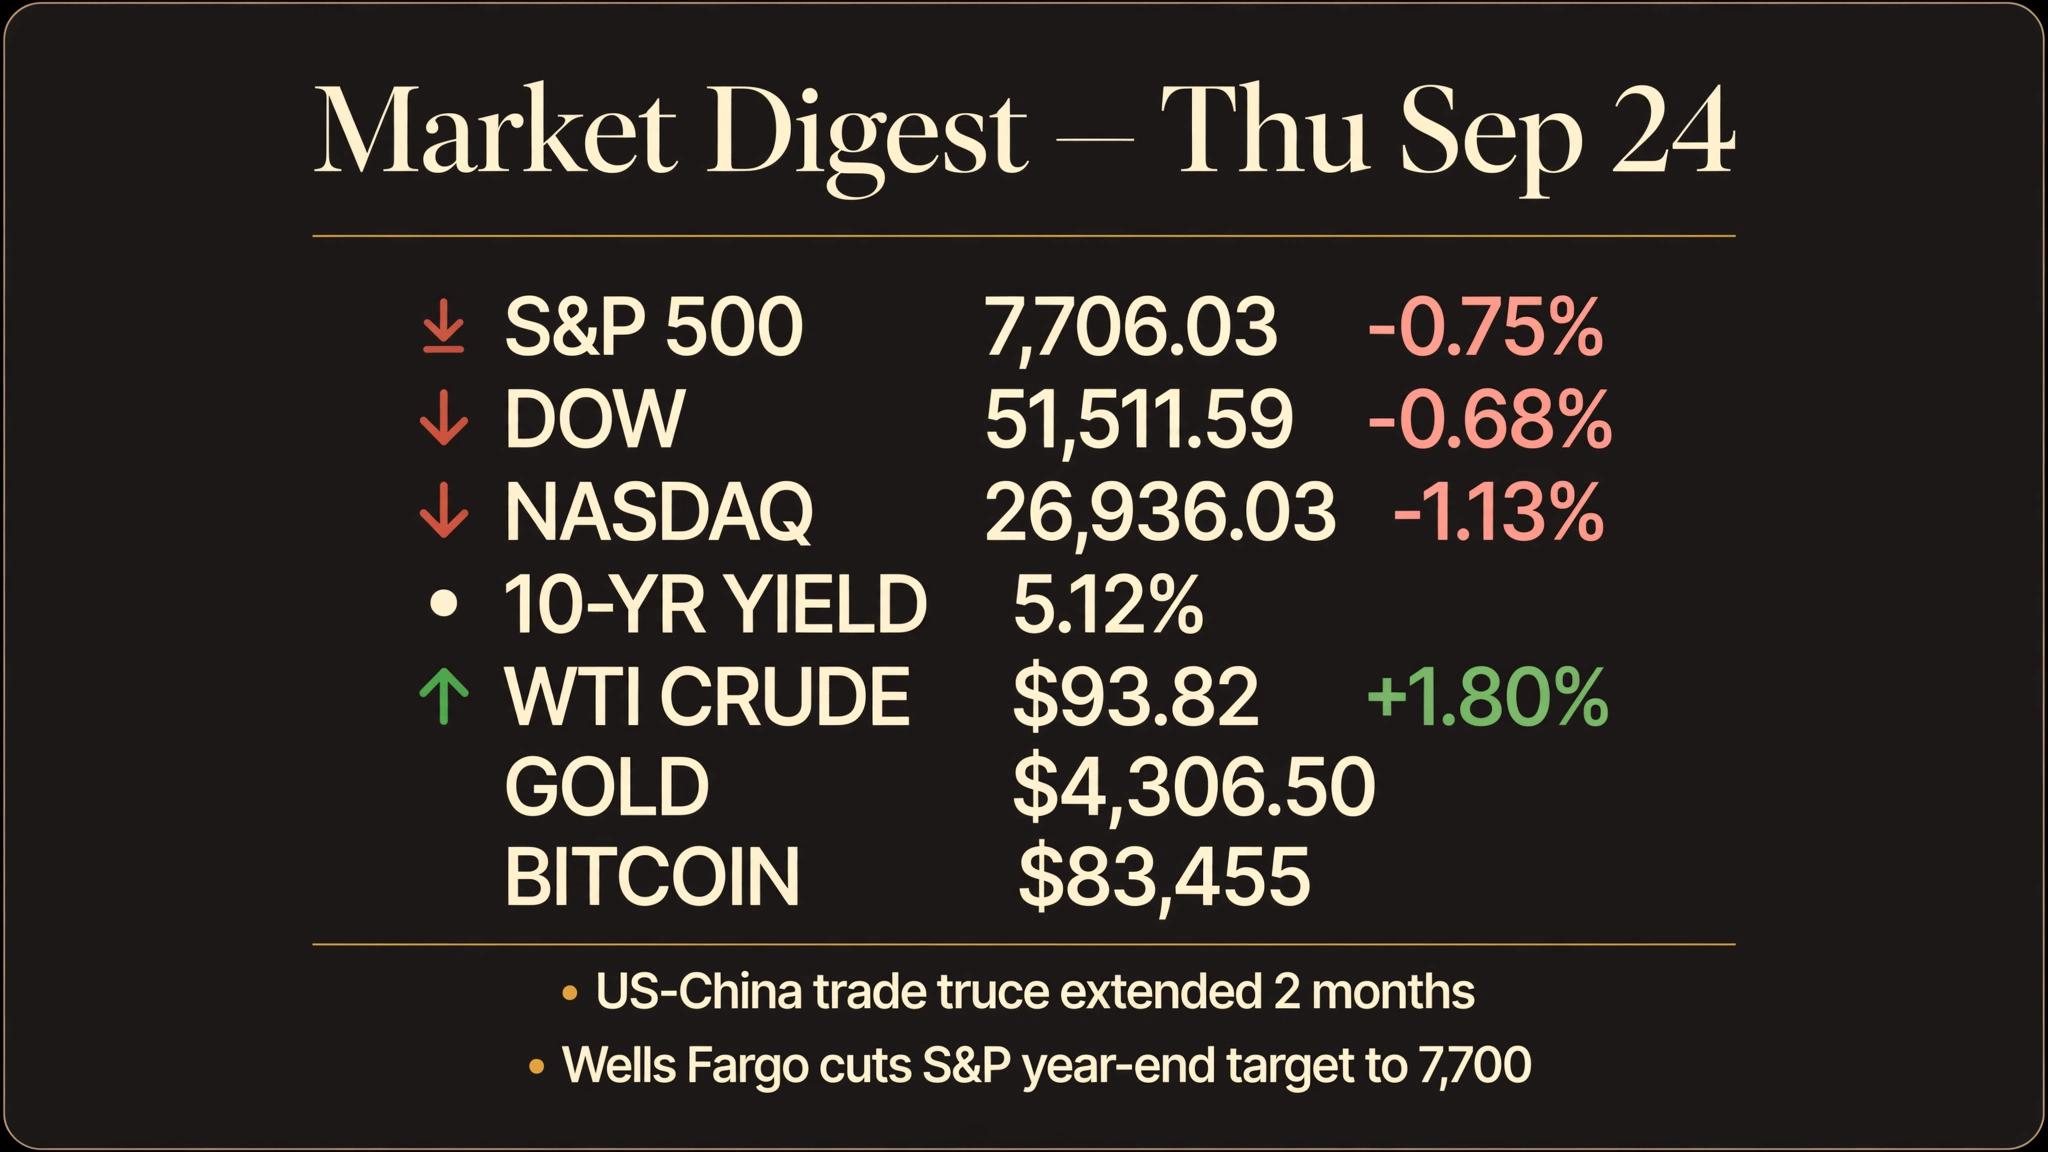
The one thing that matters: Thursday's Trump–Xi summit produced a two-month extension of the U.S.–China trade truce — but the tape belonged to the bond selloff. The 10-year yield hit 5.12%, stocks fell across the board, and Wells Fargo cut its year-end S&P target to 7,700 from 7,950, warning oil is "in the driver's seat for both stocks and bonds." Traders are pricing consecutive Fed hikes through December; with equity allocations at their widest gap over bonds since 1969, the market's message is that 5%-plus yields are the regime now.
Schwab Market Update
Thursday, Sept 24 · Morning edition (9:15 a.m. ET) — "Blistering Yield Rally Overshadows Trump-Xi Talks." Schwab's written daily article; morning snapshot below.
- Morning tape: S&P 500 7,706.03 (−0.75%), Dow 51,511.59 (−0.68%), Nasdaq 26,936.03 (−1.13%). 10-year Treasury yield 5.12% (+0.01); Dollar Index 101.28 (+0.19%); VIX 15.97 (+5.14%); gold $4,306.50 (−0.29%); WTI crude $93.82 (+$1.66, +1.80%); Bitcoin $83,455 (−1.23%).
- The story: a blistering yield rally overshadowed the Trump–Xi talks — rates, not diplomacy, set the tone for the session.
Schwab transcript not up yet — full article body wasn't retrievable tonight (site bot wall), so only the headline and the morning market snapshot are included, not summarized.
Tickers: SPX, DJIA, COMP, 10Y, DXY, VIX, GC, WTI, BTC. No individual-stock calls in today's edition.
Bloomberg The Big Take
Thursday, Sept 24 · "This Isn't Your Grandparents' UN." David Gura with Bloomberg's Annmarie Hordern and Nick Wadhams — UN General Assembly week and the Trump–Xi summit. Full transcript.
- The two big stories at UNGA: the two hot wars and AI. The episode's blunt verdict: the UN is "not at all equipped" to deal with the current crises.
- Trump's UN speech: he threatened to "annihilate Iran" from the podium — jarring, civilization-erasing rhetoric, though familiar from his first-term "fire and fury" threats — while simultaneously offering a path to a deal. U.S. mediators met the Iranians on the sidelines and called the talks productive; Bloomberg's read is it was "talks about talks," leaving things where they've been for months.
- The AI moment: the CEOs of OpenAI and Anthropic testified before the UN Security Council — the first time at that level. Outgoing Secretary-General Guterres wanted AI guardrails as the centerpiece of his second term, but the U.S. dismissed the effort as a "globalist scheme." Expect speeches, not binding rules.
- Skepticism on the AI pilgrimage: one Anthropic executive zoomed into the Security Council rather than attending in person — while the company's own employees were publicly claiming a 10%+ chance AI could "wipe out humanity." Genuine alarm or PR, the pattern is familiar: diplomats talk, break, go home, and nothing gets done.
- Trump–Xi in Washington: Xi skipped UNGA entirely — partly to focus all attention on the summit and avoid an awkward message before it. The tariff truce got another couple of months, but tariffs remain high and no CEOs traveled with Xi; there was no real industry-to-industry AI conversation.
- The strongman era vs. the institution: Erdogan used a Bloomberg op-ed to call for abolishing and reworking the Security Council. The counterpoint: UN agencies — WHO, UNICEF, the refugee agency — still do enormous humanitarian work, and U.S. funding holds and withdrawals are actively undercutting it.
The day's market callUN week changes nothing binding — the two hot wars and AI regulation remain the market's background risk. The only relationship that matters is U.S.–China, and the summit bought time, not resolution.
Tickers: none. Geopolitics drove this episode, not tickers.
Bloomberg Surveillance
Thursday, Sept 24 · "Bloomberg Surveillance TV: September 24th, 2026." Jonathan Ferro, Lisa Abramowicz, Annmarie Hordern with Osen Quan (Wells Fargo), Scott Singer (Carnegie Endowment), Ed Hosenia (Columbia Threadneedle). Full transcript.
- Wells Fargo cuts its target: Osen Quan trimmed the year-end S&P target to 7,700 from 7,950 — with oil, he says, "in the driver's seat for both stocks and bonds." He sees 5–10% downside from here.
- The allocation gap: equities now sit at 72% of allocations vs. 28% bonds — the highest since 1969. Against a 5% risk-free rate, the fair equity allocation is roughly 60%; that 12-point gap, the widest since 1969, implies essentially zero excess return on the S&P over the risk-free rate at 7% annual EPS growth.
- Earnings are cyclically elevated: 2027 EPS is expected to land ~42% above cyclically-adjusted EPS — one of the strongest 10-year EPS cycles in history, surpassed only by the post-WWII 1950s bull. That argues for lower multiples going forward.
- The oil scenarios: WTI back to $70–75 and the S&P could test 8,000 (the "pain trade" is higher near-term as hedge funds de-grossed heavily). Oil at $150–200 and the S&P is below 7,000 with recession talk back on. At $100, the consumer is still okay — no recession call.
- Nobody left to buy: retail flows are tapped out, long-onlys are fully invested, and corporates enter a buyback blackout for the next month. Expect choppy hedge-fund re-grossing/de-grossing — volatility, not trend.
- Fed path: Columbia Threadneedle's Ed Hosenia calls bonds "getting in the zone" — his baseline is consecutive hikes through December, 3–4 total, with October in play despite the election proximity. Feedback is showing up in a flattening curve, rising real rates, and a stronger dollar — but not yet in risk appetite.
- Macro strong: purchasing managers' data was the strongest since 2021 — strong growth is what's fueling the bond selloff. The Fed will "have to work harder to squeeze excess demand out of this economy."
- Summit fallout: a two-month trade-truce extension; the Energy Secretary is telling oil executives to prepare for possible diesel export curbs (decision not final); Sam Altman attended a state dinner for Xi; Carnegie's Scott Singer argued the U.S. and China should regulate frontier AI domestically first — and need a permanent channel for cross-border AI crises.
The day's market call5%-plus yields are the regime. The equity-vs-bond allocation gap is the trade, oil is the swing variable, and the Fed looks set to hike through December. Watch WTI.
Tickers: SPX, WTI/Brent, 10Y/30Y, DXY. No individual-stock calls today.
Fidelity Market Sense
Weekly — drops Tuesdays. No new episode since Week 212 (2026-09-15).
CNBC Mad Money
Thursday, Sept 24 · The "Mad Money 09/24/26 | Audio Only" upload exists on YouTube, but caption download was rate-limited today — no free text source, so the show is skipped rather than summarized from headlines.
Mad Money transcript not up yet.
CNBC Fast Money
Skipped — no free caption source (standing rule).