Daily Market Digest · Wednesday, September 30, 2026
Yields at 20-year highs, and nobody wants bonds.
Built from tonight's finance podcast transcripts — what the shows actually said, paraphrased, never invented. Sources that weren't available are marked inline.
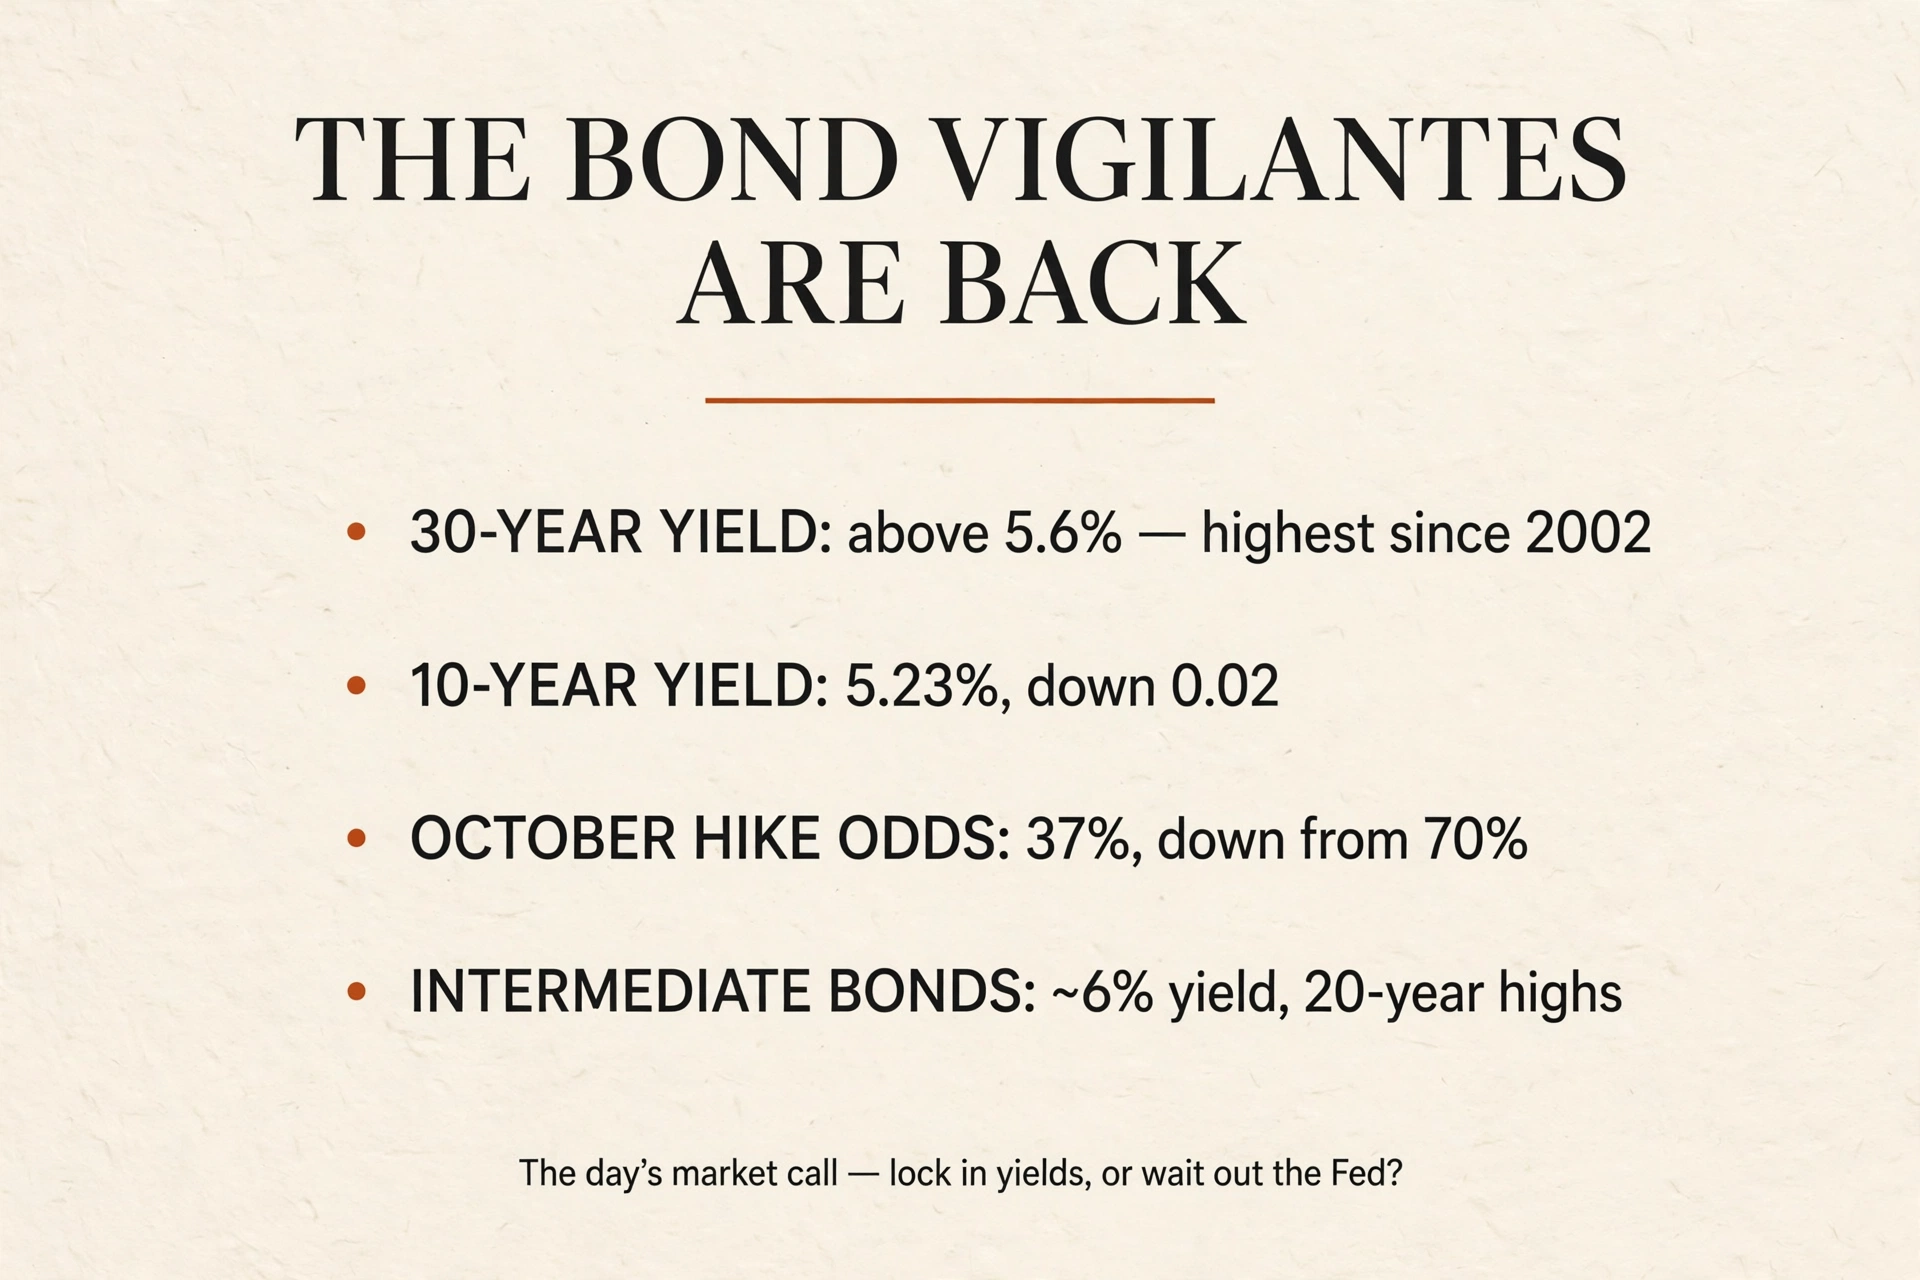
The one thing that matters: the 30-year Treasury broke above 5.6% — its highest since 2002 — and bond investors are refusing to buy the dip ("we are in a high-yield bond world and no one wants anything to do with it"). But today's August PCE came in cooler than expected, cutting October rate-hike odds from 70% to 37% and giving the market a one-day reprieve. Friday's payrolls report now decides whether the Fed gets to stand down — and whether these generational yields get locked in or run even higher.
Schwab Market Update
Wednesday, Sept 30 · Morning edition (9:13 a.m. ET) — "Inflation Growth Slows, Sending Stocks Up Early." Article content via search-index cache; full text behind Schwab's bot wall.
- Cooler PCE: August Personal Consumption Expenditures rose 0.3% headline and 0.2% core, below the 0.4%/0.3% consensus. Stocks edged up; the 10-year eased to 5.23%.
- But the Fed isn't done, per Schwab: Cooper Howard (SCFR) — "I don't think that it changes the story with the Fed. We still expect at least one more hike this year and potentially another either later this year or early next year."
- October hike odds halved: down to 37% after John Williams said only one more hike "late this year" might be appropriate. Friday's nonfarm payrolls (seen at 84,000) is the next decision point.
- Oil's quarter: WTI at $90.41 (+1.13%) and up 42% this quarter. Gold $4,240 (+1.46%), Bitcoin $85,870 (+2.31%), VIX 15.85.
- September scorecard: S&P 500 down 0.2%, Nasdaq-100 up 3%, Dow down 3.5%, Russell 2000 off 5%.
The day's market callInflation cooled just enough to halve October hike bets, but the tape is still owned by the long end. Everything now waits on Friday's jobs number.
Tickers: SPX, DJIA, NDX, RUT, TNX, VIX, WTI, GC, BTC.
Bloomberg The Big Take
Wednesday, Sept 30 · "Can $700 Million Buy Republicans the US Senate?" Full transcript via official Bloomberg Podcasts YouTube auto-captions. Guests: Bill Allison (campaign finance) and Bill Faries (midterms coverage).
- Record spending: Republicans hold roughly a $700M-to-$450M spending advantage on the Senate side. Trump's super PAC raised over $400M — "never been a president that has done this."
- The coordination game-changer: a June Supreme Court ruling lifted limits on national parties spending in coordination with campaigns. The NRSC outspent its Democratic counterpart on ads 46-to-1 in August, letting party money act like candidate money (lowest-unit ad rates included).
- The Musk factor: Elon Musk's super PAC has put in $20M+ and is just getting going — a wild card in the final weeks.
- New industry money: gambling/sports-betting super PACs, and AI super PACs that spend on both sides of races — a new corporate-interest wave beyond traditional partisan groups.
- Democrats' counter: small-dollar dominance — ActBlue raises ~3x what WinRed does. GOP candidates trail Democratic candidates in their own fundraising (e.g., in Texas, only ~$600k of $170M booked since Sept 1 came from Paxton's campaign), giving Democrats more message control.
- Surprise battlegrounds: Kansas, Iowa, and Ohio are suddenly in play, driven by cost-of-living frustration and spiking diesel prices in farm country. Texas is eating GOP money it normally wouldn't need to spend.
- Looking to 2028: expect much more expensive primaries and candidates running their own super PACs — the party-coordination channel stays open.
The day's market callFive weeks out, Senate control may rest on which toss-up states the Republican money wall can actually buy — and Democrats' small-dollar army could make election night stretch for days.
Tickers: none — politics edition. Key: record midterm spend, SCOTUS coordination ruling.
Bloomberg Surveillance
Wednesday, Sept 30 · TV edition (YouTube -03fNDyc0rE). Full transcript via official YouTube auto-captions. Guests: Matt Miskin (John Hancock), Francisco Blanch (Bank of America), Stephanie Roth (Wolfe Research).
- Buyers' strike at the long end: the 30-year pushed above 5.6% — highest since 2002 — and investors wouldn't touch it even on weak consumer-confidence/JOLTS data. Equity love, bond loathing: "every stock on the planet is loved, every bond on the planet is disliked."
- Lock-in-the-yield argument (Miskin): intermediate bonds yield ~6% — 20-year highs and "a ton of value." Rotation call: quality value, healthcare, industrials — tech is fine but the AI trade has no breadth (semis, then everything else left behind). Q3 S&P earnings growth tracking ~28%.
- The 2027 warning: this quarter's earnings are flattered by private-investment write-ups of AI companies pre-IPO — "base effects are going to be tough" next year, with higher cost of capital and energy costs. Yields likely lower into next year; equities "passing peak growth."
- Diesel crisis talks (Blanch): the FT reports the White House is in crisis talks over a proposed diesel export ban. Blanch: a ban needs US shipping capacity to avoid shortages, could cut refinery runs and lift gasoline, and hinges on Europe releasing reserves. The Hormuz blockade is working — Persian Gulf supplies up, Iranian exports down — but at $20+/barrel shipping and two carrier groups' cost. China's inventories are falling 2–3M barrels/day, which may push Beijing toward a deal.
- Roth on PCE: the print "barely rounded down" (0.247 → 0.2) and revisions came from methodology changes, not disinflation — "we're fighting 3% inflation on core PCE," with diesel prices feeding tomorrow's core goods. The Fed probably hikes at least once more, maybe twice. Friday payrolls base case: 70k, unemployment 4.2%, wages 0.3%. Oct 14 CPI is the next flashpoint.
The day's market callBuyers are on strike at 5.6%, but the strategists' bet is these yields mark the top, not the start of a spiral. The verdict arrives Friday, not today.
Tickers: none named; key: TNX, crude/diesel complex, Hormuz flows.
Fidelity Market Sense
Weekly — drops Tuesdays. No new episode today; the latest remains the 09.22.26 edition ("The biggest ETF trends investors should know now").
CNBC Mad Money
Skipped — the "Mad Money 09/30/26 | Audio Only" upload exists but caption download hit a YouTube 429; no retry per rate-limit policy, and the show is never summarized from headlines.
CNBC Fast Money
Skipped — no free caption source (standing rule).